Ramly Mokni Success Story
Discover the Ramly Mokni success story and how he transformed a small halal burger business into one of Malaysia’s most iconic food brands.
Explore the Astro Business Model Canvas, including all nine BMC blocks, Value Proposition Canvas, Netflix and Unifi TV comparison, competitive advantages, risks and strategic recommendations updated for 2026.
BMC Article No: BMC #020
Updated in 2026: This article has been comprehensively updated to reflect Astro’s continuing transformation from a traditional satellite television operator into a broader media, entertainment, streaming, connectivity and advertising ecosystem. The updated Astro Business Model Canvas considers Astro One, NJOI, Sooka, Astro GO, Astro Fibre, streaming aggregation, enterprise solutions, digital advertising and the introduction of Astro X3.
The 2026 edition also provides deeper analysis of every Business Model Canvas block, an expanded closing analysis for each component, a Value Proposition Canvas, comparison with Netflix and Unifi TV, competitive advantages, risks and challenges, and strategic recommendations.
Astro Malaysia Holdings Berhad has long been one of Malaysia’s most recognisable media companies. What began primarily as a pay-TV proposition has progressively expanded across satellite television, connected boxes, streaming, radio, broadband, digital media, advertising, content production and enterprise solutions.
The strategic environment, however, has changed considerably. Global streaming platforms have increased consumer choice, piracy remains a structural problem, household spending is under pressure, and audiences increasingly expect entertainment to work across televisions, smartphones and connected devices. Astro itself acknowledges that audiences are fragmenting and consumers are becoming more value-conscious.
This makes the Astro Business Model Canvas particularly useful because Astro can no longer be evaluated simply as a subscription-TV company. Its future depends on connecting several businesses around content, customer reach, technology, connectivity and monetisation.
Astro reported 5.2 million TV households in FY26, representing 63% household penetration, alongside 920,000 Sooka monthly active users, 524,000 Astro GO monthly active users and 9,100 enterprise customers.
Astro operates an integrated media and entertainment model built around producing, acquiring, aggregating, distributing and monetising content.
Traditionally, subscription television formed the economic centre of the business. Customers paid monthly fees for access to entertainment, movies, sports, news and vernacular programming through Astro’s television platform.
That foundation is becoming broader.
The Astro Business Model Canvas now includes three differentiated video propositions: pay-TV for households seeking comprehensive entertainment, NJOI for more flexible prepaid consumption, and Sooka for digital-first streaming audiences. Astro also generates value through broadband, enterprise services, advertising, radio, digital brands, production services and content-related activities.
Aggregation is another important element. Rather than treating every international streaming platform solely as a competitor, Astro increasingly integrates external streaming services into its own bundles. New combinations involving Disney+ and Prime Video, for example, were introduced in June 2026.
The resulting strategy is moving Astro from being primarily a channel distributor toward becoming an entertainment gateway.
Digital disruption initially threatened Astro by giving consumers alternatives to conventional pay-TV. Streaming services reduced dependence on scheduled broadcasting, while mobile devices changed where and how entertainment was consumed.
Astro’s response has progressively shifted from defending traditional television toward participating in the same digital behaviour causing the disruption.
Astro GO extends content to existing customers on connected devices. Sooka provides a digital-first proposition that can reach customers outside conventional pay-TV. Astro One simplifies packaged entertainment, while connected boxes integrate streaming applications with linear television.
The July 2026 introduction of Astro X3 pushed this transition further. Astro described X3 as a streaming-first service requiring no box, installation or contract, with mobile sign-up designed to make access considerably simpler.
Digital adaptation therefore involves more than creating another application. Astro is redesigning packaging, distribution, pricing, partnerships and customer journeys around lower friction.
This evolution makes the Astro Business Model Canvas increasingly platform-oriented rather than infrastructure-oriented.
Astro operates across several overlapping entertainment markets.
Its home segment includes pay-TV, connected boxes, NJOI and broadband. Individual consumers can also access Sooka, Astro GO, radio stations and digital brands. Commercial customers receive enterprise entertainment, connectivity and advertising solutions.
Content remains central. Astro reported producing 11,600 hours of content during FY26 and investing RM370 million in local content. Its content strategy covers local vernacular programming, live sports, kids, news, regional programming and international entertainment.
Scale remains significant. FY26 figures included 71% share of TV viewership, 16.2 million weekly radio listeners across FM and online, and 18.9 billion video views across pay-TV, Sooka and NJOI.
Financially, Astro reported FY26 revenue of RM2.8 billion, PATAMI of RM63 million and free cash flow of RM459 million.
The strategic question is therefore not whether Astro still possesses reach. It is how effectively that reach can be converted into sustainable customer and advertiser value as media consumption continues moving across platforms.
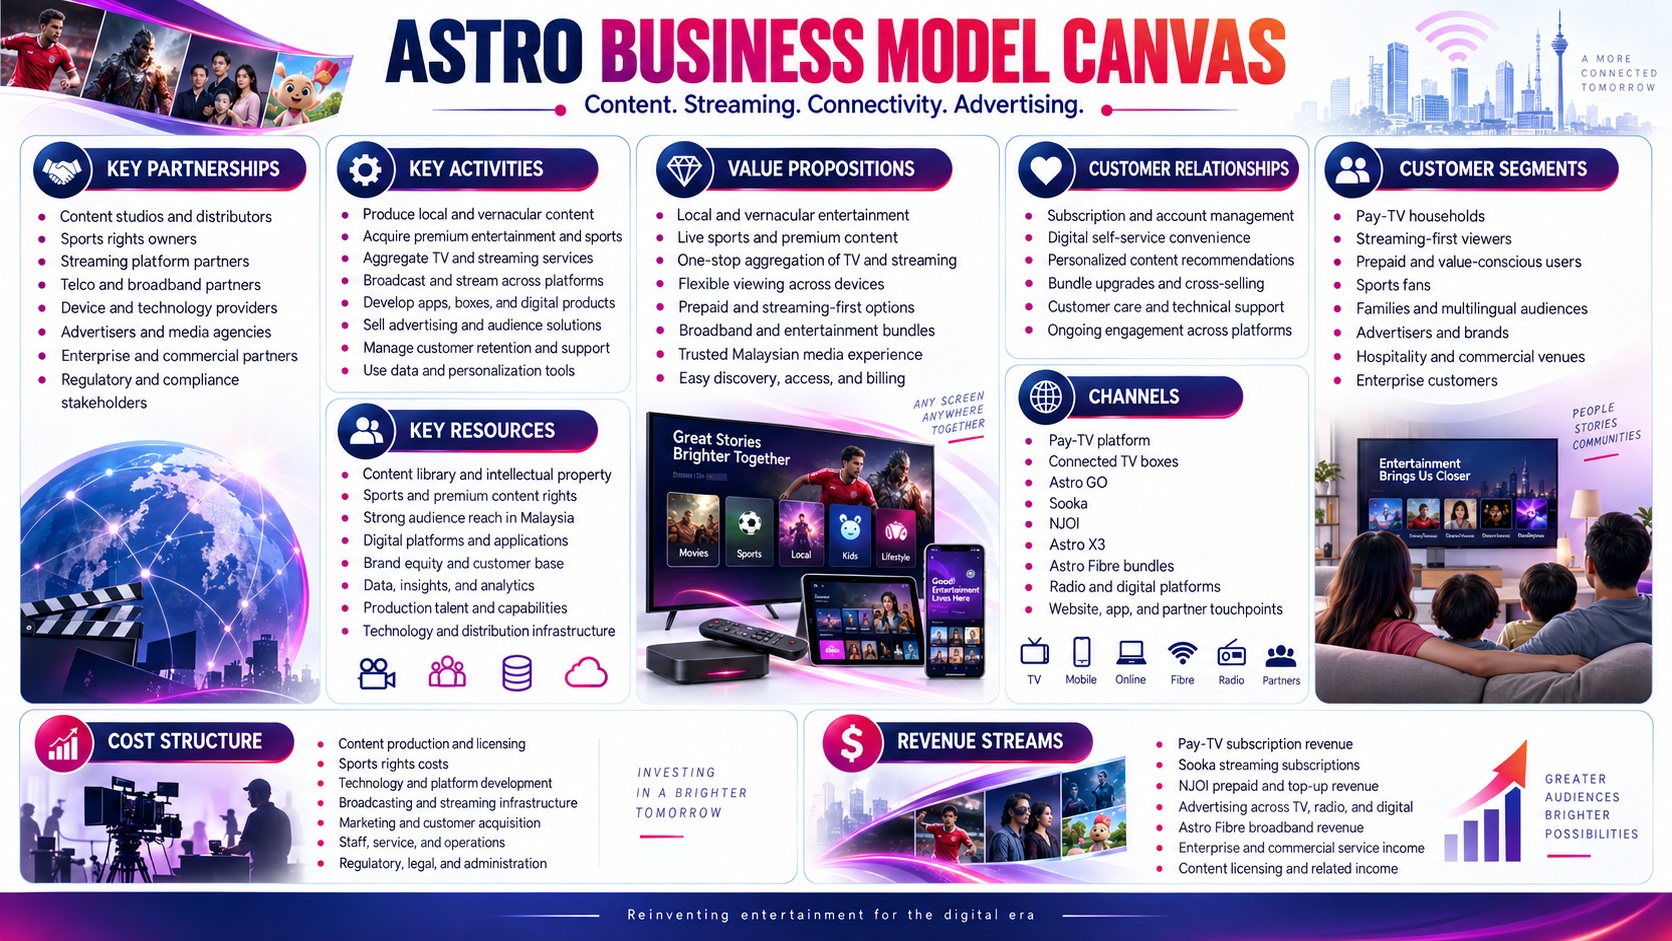
Before examining each component individually, the Astro Business Model Canvas can be summarised as an integrated system that turns content, distribution capabilities and audience reach into subscription, advertising, connectivity and related revenues.
| BMC Block | Astro Application |
|---|---|
| Customer Segments | Pay-TV households, prepaid users, streaming audiences, sports fans, advertisers and enterprises |
| Value Propositions | Local content, live sports, aggregation, flexible access, affordability and convenience |
| Channels | Pay-TV, Astro GO, Sooka, NJOI, Astro X3, radio, digital platforms and enterprise channels |
| Customer Relationships | Subscription management, self-service, personalisation, customer support and digital engagement |
| Revenue Streams | Subscriptions, prepaid purchases, advertising, broadband, enterprise and content-related income |
| Key Resources | Content IP, rights, brands, platforms, technology, audiences, talent and infrastructure |
| Key Activities | Content creation, acquisition, aggregation, distribution, streaming, advertising and product development |
| Key Partnerships | Studios, sports rights owners, streaming platforms, telcos, technology providers and advertisers |
| Cost Structure | Content, rights, technology, distribution, talent, marketing and operations |
The individual blocks matter, but Astro’s transformation succeeds only when they work together.
The Astro Business Model Canvas reveals a company attempting to preserve the economics of a large established media platform while creating enough flexibility to compete in a fragmented streaming environment.
Content attracts audiences. Multiple distribution models broaden accessibility. Customer reach supports subscriptions and advertising. Revenue then funds new programming, technology and platform development.
Each block also creates strategic trade-offs.
Premium sports can strengthen customer retention but increase content costs. Lower entry pricing can expand accessibility but pressure average revenue per user. Streaming partnerships improve convenience while increasing dependence on external content providers.
The following sections examine those dynamics in greater depth.
Astro serves customer groups with significantly different willingness to pay, content preferences and consumption habits.
Traditional pay-TV households remain important, particularly families seeking broad entertainment, vernacular programming, news and live sports. NJOI reaches more price-sensitive customers through prepaid access, while Sooka targets digital-first users who may prefer flexible streaming.
Astro also serves advertisers seeking access to television, radio and digital audiences. Hotels, restaurants, commercial premises and other organisations represent another segment through enterprise offerings.
| Segment | Details | Why It Matters |
|---|---|---|
| Pay-TV households | Families purchasing packaged entertainment | Supports recurring revenue |
| Digital-first viewers | Sooka and streaming-led customers | Builds future audience growth |
| NJOI users | Flexible prepaid entertainment customers | Extends market coverage |
| Advertisers | Brands buying TV, radio and digital exposure | Diversifies monetisation |
| Enterprise customers | Hospitality and commercial organisations | Creates B2B revenue |
Segmentation has become strategically important because a single subscription model cannot efficiently serve the entire Malaysian entertainment market.
The Astro Business Model Canvas works best when customers can enter the ecosystem at different price points while Astro progressively increases engagement and lifetime value. Rather than forcing every viewer into traditional pay-TV, Astro can use multiple propositions to prevent customers from leaving its ecosystem entirely.
Astro’s strongest proposition is increasingly the combination of local relevance and entertainment aggregation.
Malaysian audiences receive vernacular programming, local productions, news and sports alongside international movies, series and streaming applications. This breadth helps Astro position itself as an entertainment gateway rather than one isolated streaming service.
Convenience adds another layer. Connected boxes, Astro GO and integrated streaming applications reduce the need for customers to move repeatedly between different services.
| Value Proposition | Details | Why It Matters |
|---|---|---|
| Local relevance | Malaysian and vernacular programming | Differentiates Astro from global platforms |
| Live sports | Premium domestic and international sports | Creates appointment viewing |
| Content aggregation | Linear TV plus multiple streaming services | Reduces entertainment fragmentation |
| Flexible access | Pay-TV, prepaid and streaming options | Serves different budgets |
| Convenience | Integrated discovery, billing and devices | Reduces customer friction |
Astro’s strategic advantage is therefore not simply having more channels.
International streamers may possess enormous global content libraries, but Astro can combine local programming, sports, news, broadband and third-party streaming within one relationship.
The Astro Business Model Canvas becomes stronger when this convenience is sufficiently clear that customers perceive aggregation as valuable rather than merely another bundle. Sustainable differentiation requires Astro to remain locally distinctive while making entertainment simpler.
Astro has evolved from a predominantly satellite-distribution model into a multi-channel entertainment business.
Traditional television remains important, but connected boxes increasingly combine linear programming, on-demand content and streaming applications. Astro GO provides supplementary mobile and online access for eligible customers.
Sooka establishes a direct digital channel for streaming audiences, while NJOI provides prepaid access. Astro X3 further reduces distribution friction through a streaming-first proposition without a box, installation or contract.
| Channel | Details | Why It Matters |
|---|---|---|
| Pay-TV platform | Television packages and connected boxes | Maintains household presence |
| Astro GO | Multi-device access for customers | Extends viewing beyond television |
| Sooka | Digital-first OTT platform | Reaches streaming audiences |
| NJOI | Prepaid television proposition | Serves value-conscious segments |
| Astro X3 | Streaming-first direct access | Reduces installation and contract friction |
Distribution flexibility reduces reliance on a single technology.
Astro’s historical satellite infrastructure created scale but also associated the brand strongly with conventional television. Digital channels can reshape that perception.
Long-term success will depend on creating seamless movement across screens, subscriptions and products so customers experience Astro as one entertainment ecosystem rather than several disconnected services.
Astro’s customer relationships combine recurring subscriptions, digital self-service, personalised engagement and direct customer support.
Pay-TV historically produced relatively structured relationships through monthly subscriptions, installation and service interactions. Streaming changes that dynamic because consumers can switch providers much more easily.
Retention must consequently come from continuing value rather than contractual friction.
Digital account management, recommendations, promotions, package upgrades and cross-selling between entertainment and connectivity can strengthen engagement. Customer care remains particularly important when services involve hardware, billing or broadband.
| Relationship Type | Details | Why It Matters |
|---|---|---|
| Subscription relationship | Ongoing monthly packages | Creates recurring engagement |
| Digital self-service | Apps and account-management tools | Lowers service friction |
| Personalisation | Recommendations and tailored experiences | Improves relevance |
| Customer support | Technical and account assistance | Protects satisfaction |
| Cross-service engagement | Content, broadband and streaming bundles | Increases customer value |
Competition makes relationship quality increasingly important.
Customers can now compare entertainment subscriptions quickly and cancel services with less inconvenience than during the traditional pay-TV era. Astro must therefore understand churn indicators, content consumption, pricing sensitivity and service experience.
Trust, affordability and ease of use can become retention mechanisms as important as exclusive programming.
Subscription revenue remains fundamental, but Astro’s monetisation model is becoming more diversified.
Pay-TV generates recurring household revenue, while NJOI provides prepaid monetisation. Sooka creates streaming income through digital packages, and Astro Fibre adds connectivity revenue.
Advertising contributes another source through television, radio, streaming and digital inventory. Enterprise customers expand monetisation into commercial environments, while content production, licensing and related activities provide additional opportunities.
| Revenue Stream | Details | Why It Matters |
|---|---|---|
| Pay-TV subscriptions | Monthly entertainment packages | Core recurring income |
| Streaming and prepaid | Sooka and NJOI purchases | Captures flexible demand |
| Advertising | TV, radio, digital and streaming inventory | Monetises audience attention |
| Broadband | Astro Fibre services and bundles | Diversifies household revenue |
| Enterprise and content | Commercial services and IP-related income | Extends beyond consumers |
FY26 revenue was RM2.8 billion, while free cash flow reached RM459 million.
Revenue diversification is important because traditional pay-TV economics are under pressure.
The Astro Business Model Canvas becomes more resilient when the company can monetise the same underlying audience and content capabilities through subscriptions, advertising, connectivity, enterprises and intellectual property rather than relying excessively on one monthly television package.
Astro’s most important resources extend well beyond satellites and set-top boxes.
Content rights and proprietary intellectual property are fundamental because audiences ultimately pay attention to programming rather than distribution technology. Local production capability provides another strategic asset.
Brand recognition, established customer relationships, advertising reach, radio audiences and distribution infrastructure strengthen the ecosystem.
Technology platforms have also become more important as streaming, personalisation and connected devices expand.
| Key Resource | Details | Why It Matters |
|---|---|---|
| Content and IP | Owned and licensed programming | Drives audience demand |
| Sports rights | Premium live sporting content | Supports acquisition and retention |
| Brand and reach | Large established Malaysian presence | Reduces customer-acquisition barriers |
| Technology platforms | Streaming, apps and connected infrastructure | Enables digital transformation |
| Talent and production | Creative, editorial and technical capability | Supports differentiated local content |
Astro describes itself as Malaysia’s largest content creator and identifies content IP, brand reputation, software, systems and proprietary information as intellectual capital.
Physical distribution once represented the dominant competitive barrier.
Today, intellectual property, data, technology, customer relationships and local creative capabilities increasingly determine strategic value. Astro must therefore continue shifting investment toward resources that remain differentiated even when viewers no longer depend on satellite distribution.
Astro performs several activities simultaneously to keep its ecosystem functioning.
Content creation and acquisition sit at the centre. The company must commission local productions, secure external programming, manage sports rights and maintain sufficient variety across customer segments.
Distribution is equally critical. Television broadcasting now operates alongside on-demand delivery, streaming applications, connected boxes and digital platforms.
Advertising operations convert audience attention into commercial revenue, while product development improves user interfaces, recommendations, bundles and customer journeys.
| Key Activity | Details | Why It Matters |
|---|---|---|
| Content creation | Produce local and vernacular programming | Builds differentiation |
| Content acquisition | License sports and international programming | Expands entertainment breadth |
| Distribution | Operate TV, streaming and digital delivery | Reaches customers everywhere |
| Product development | Improve apps, boxes and customer journeys | Supports digital competitiveness |
| Advertising operations | Monetise audience across platforms | Creates non-subscription income |
The company produced 11,600 hours of content during FY26 and has identified expansion of local IP and live content as a strategic priority.
Execution complexity is increasing because Astro must simultaneously behave like a broadcaster, streaming platform, content studio, aggregator, advertising network and connectivity provider.
Operational discipline is therefore essential. Adding services only creates value when the combined customer experience remains simple.
Astro’s business depends heavily on external ecosystems.
International studios and content owners provide movies, series and channels. Sports organisations and rights holders supply premium live events that can influence subscription decisions.
Streaming companies are increasingly both competitors and partners. Integrating third-party applications can make Astro more useful even when some viewing shifts away from Astro-owned channels.
Telecommunication, technology and device partners also support distribution and customer acquisition.
| Key Partner | Details | Why It Matters |
|---|---|---|
| Content owners | Studios, broadcasters and distributors | Expands programming choice |
| Sports rights holders | Leagues and event owners | Supports premium sports proposition |
| Streaming platforms | Integrated OTT applications | Strengthens aggregation |
| Technology partners | Devices, software and infrastructure | Enables digital delivery |
| Telcos and advertisers | Distribution and commercial partners | Expands reach and monetisation |
Sooka illustrates this ecosystem strategy. In March 2026, CelcomDigi added Sooka to its StreamMORE offering, creating another route for Astro’s streaming product to reach consumers.
Partnerships allow Astro to offer more than it could create internally.
Strategic risk arises when important content owners, technology platforms or distribution partners gain too much bargaining power. Astro therefore needs partnerships that enhance aggregation while protecting its direct customer relationship and local differentiation.
Astro operates a cost-intensive media business.
Content represents a major investment area. Producing original programming, acquiring international content and securing sports rights require substantial expenditure before the audience or revenue outcome is fully known.
Technology adds another cost layer as Astro supports broadcasting infrastructure, streaming platforms, connected boxes, cybersecurity, software development and digital customer experiences.
Marketing, customer service, talent, transmission and corporate operations contribute further expenditure.
| Cost Area | Details | Why It Matters |
|---|---|---|
| Content investment | Local productions and licensed programming | Essential for differentiation |
| Sports rights | Premium event and league rights | Supports high-value audiences |
| Technology | Streaming, software, platforms and devices | Enables digital transition |
| Distribution | Broadcasting and connectivity infrastructure | Maintains service reliability |
| Operations | Staff, marketing and customer support | Supports the wider ecosystem |
Astro invested RM370 million in local content during FY26.
Cost discipline becomes increasingly important as customers demand lower prices while premium content remains expensive.
Reducing expenditure indiscriminately could weaken programming and accelerate churn. Successful transformation instead requires shifting resources from legacy costs toward differentiated content, scalable technology and activities capable of producing measurable engagement, retention or new revenue.
The Astro Business Model Canvas creates the most insight when its nine elements are viewed as one connected economic system.
Customer segments determine which entertainment propositions Astro must create. Families may prefer comprehensive bundles, digital-first viewers may choose Sooka or X3, price-sensitive households may prefer NJOI, and businesses require specialised commercial solutions.
Content, live sports and aggregation form the value proposition. Television, connected boxes, applications and streaming services then deliver that value across different channels.
Strong customer relationships improve retention and create opportunities to cross-sell connectivity or additional entertainment.
Revenue from subscriptions, advertising, broadband and enterprise customers subsequently funds content, technology and distribution.
Key partnerships expand content availability and market reach, while resources such as IP, brand, audience scale and technology support continued execution.
Problems arise when the system becomes unbalanced.
Expensive content without sufficient engagement destroys value. Lower prices without cost efficiency damage margins. Too many packages create complexity rather than choice.
Astro therefore needs every BMC block to reinforce the others around a simple strategic objective: making high-quality Malaysian and international entertainment easier to access and monetise across platforms.
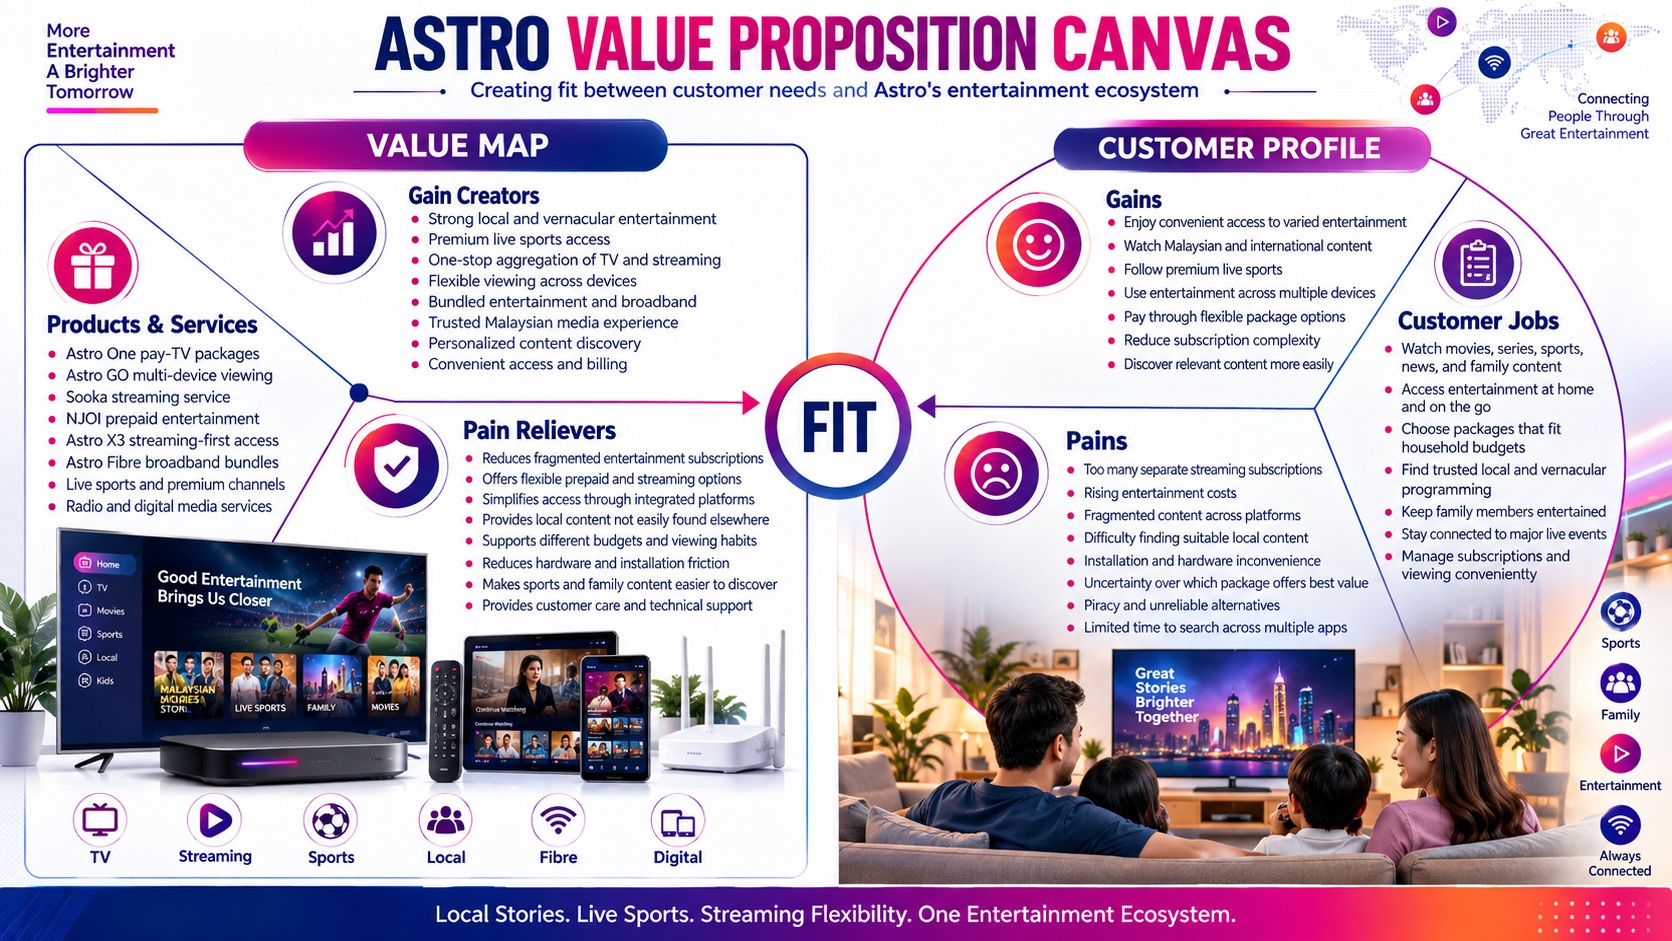
The Astro Business Model Canvas explains the overall economic architecture, while the Value Proposition Canvas provides a closer view of why household customers might continue choosing Astro in a fragmented entertainment market.
The primary customer considered here is a Malaysian household seeking convenient access to local and international entertainment.
Households increasingly manage several competing entertainment priorities. They want choice, but excessive subscriptions create cost and complexity.
| Customer Profile | Details |
|---|---|
| Customer Jobs | Watch entertainment, live sports, news and family programming conveniently across devices |
| Customer Pains | Multiple subscriptions, rising costs, fragmented content, piracy alternatives, installation friction and difficulty finding programmes |
| Customer Gains | Relevant local content, premium sports, convenient bundles, flexible pricing and simple multi-device access |
Astro’s challenge is therefore broader than delivering television.
Customers increasingly expect control over what they buy, where they watch it and how much they pay.
A strong customer profile recognises that convenience and affordability have become part of the entertainment product itself.
Astro addresses those requirements through a portfolio rather than one universal product.
| Value Map | Details |
|---|---|
| Products and Services | Astro One, connected boxes, Astro GO, Sooka, NJOI, Astro X3, Astro Fibre, radio and streaming bundles |
| Pain Relievers | Aggregated subscriptions, flexible streaming, prepaid options, digital access and simplified packages |
| Gain Creators | Local IP, live sports, multilingual content, international streaming, multi-device viewing and integrated entertainment |
Aggregation can reduce subscription fragmentation, while Sooka and X3 remove some of the hardware and commitment associated with traditional pay-TV.
NJOI addresses affordability differently through prepaid access.
The portfolio therefore allows Astro to respond to different combinations of convenience, content preference and willingness to pay rather than treating every household identically.
| Customer Profile | Details | Matching Value Map | How Astro Creates Fit |
|---|---|---|---|
| Customer Jobs | Access varied entertainment | Products and Services | Multiple platforms cover TV and streaming |
| Customer Pains | Fragmented subscriptions and high costs | Pain Relievers | Bundling, prepaid and flexible products simplify access |
| Customer Gains | Local relevance, sports and convenience | Gain Creators | Content, aggregation and multi-device access increase value |
Value fit improves when Astro simplifies entertainment rather than adding complexity.
Customers should immediately understand which proposition best matches their budget and viewing behaviour.
That requirement makes product architecture increasingly important. Too many overlapping plans could recreate the very fragmentation Astro is attempting to solve.
The Astro Business Model Canvas shares characteristics with both Netflix and Unifi TV, although the strategic foundations are different.
Netflix is fundamentally a global streaming entertainment platform increasingly combining subscriptions with advertising in selected markets. Its advertising business has expanded substantially, with Netflix reporting more than 250 million global monthly active viewers on its ads offering in 2026.
Unifi TV operates closer to Astro’s aggregation model. Its current proposition combines live channels with streaming applications and configurable packages, while also benefiting from integration with Unifi’s telecommunications ecosystem.
| Relevant BMC Block | Astro | Netflix | Unifi TV |
|---|---|---|---|
| Customer Segments | Households, streaming users, prepaid viewers, enterprises and advertisers | Global streaming subscribers and advertisers | Malaysian broadband and entertainment customers |
| Value Proposition | Local content, sports, aggregation and multi-platform access | Large global streaming library and personalised entertainment | Flexible channel and streaming bundles |
| Channels | Pay-TV, Sooka, GO, NJOI, X3 and connected boxes | Streaming applications and connected devices | Unifi TV 2.0, TV Box, web and mobile |
| Revenue Streams | Subscriptions, prepaid, ads, broadband and enterprise | Subscriptions and advertising | TV packages, streaming bundles and telco relationships |
| Key Resources | Local IP, sports, audience reach, brand and platforms | Global content, recommendation technology and scale | Connectivity ecosystem, aggregated content and distribution |
Astro occupies a distinctive middle position.
Netflix has far greater global streaming scale, while Unifi can integrate entertainment tightly with telecommunications.
Astro’s strongest response is not attempting to imitate either competitor completely. Its differentiation comes from combining Malaysian content leadership, live sports, established household reach, advertising inventory and aggregation within one ecosystem.
Several structural strengths give the Astro Business Model Canvas defensible advantages within Malaysia’s entertainment market.
These advantages reinforce one another when managed effectively.
Local IP creates differentiation, reach attracts advertisers, advertising supports monetisation, sports strengthens engagement and aggregation increases convenience.
Astro’s strategic challenge is converting established scale into digital-era relevance before legacy advantages weaken further.
Astro continues to face significant structural and execution risks despite its market position.
The greatest threat may not be a sudden collapse in demand.
Gradual erosion could be more damaging if pay-TV revenue weakens faster than streaming, advertising, broadband and enterprise businesses can scale.
Management must therefore balance transformation speed with financial discipline.
Astro should continue repositioning itself from a traditional pay-TV operator toward Malaysia’s integrated entertainment platform.
The objective should not be to abandon television prematurely. Instead, the company should use its existing household reach, content capabilities and brand to accelerate businesses suited to changing consumer behaviour.
Each strategic initiative should strengthen multiple BMC blocks simultaneously.
Astro should make simplicity one of its strongest competitive advantages.
Consumers increasingly face multiple applications, bills and subscription decisions. Astro can reduce that friction by becoming the interface through which households discover, purchase and consume a broad entertainment portfolio.
Bundling should remain understandable rather than creating excessive package complexity.
Success would allow Astro to compete on convenience even when individual programmes originate from third-party streaming services.
Sooka and Astro X3 provide Astro with mechanisms to acquire customers without traditional hardware or installation.
Digital onboarding should become exceptionally simple, with rapid registration, transparent pricing, flexible payment and immediate viewing.
The July 2026 launch of X3 demonstrates movement in this direction.
A stronger streaming-first journey can help Astro reach younger users and households unwilling to commit initially to conventional pay-TV.
Astro should increase the commercial value of successful local intellectual property rather than measuring content primarily through television ratings.
Strong Malaysian programmes can generate streaming engagement, advertising, sponsorship, licensing, events, merchandising, regional distribution and spin-offs.
Astro has already identified regional distribution and broader IP monetisation as future priorities.
Developing franchises with economic value beyond their first broadcast can improve returns on content investment.
Sports should function across television, streaming, advertising and commercial venues rather than merely as premium television channels.
Short-form highlights, companion content, interactive formats, sponsorship, statistics, community engagement and targeted streaming packages can broaden monetisation.
Local sports properties could also give Astro greater control over rights economics compared with relying entirely on expensive international competitions.
The objective should be increasing lifetime value generated from sports audiences across multiple platforms.
Sooka can expand more efficiently when customer acquisition is shared with telcos, device manufacturers, payment providers and other distribution partners.
The CelcomDigi relationship illustrates how bundling can expose Sooka to additional audiences.
Further partnerships could reduce acquisition costs while increasing Sooka’s relevance outside the traditional Astro customer base.
Growth should nevertheless prioritise paying engagement and retention rather than monthly active users alone.
Astro possesses audience relationships across television, radio, streaming and digital media.
Combining those touchpoints can create more sophisticated advertising propositions based on measurable reach, audience segments and outcomes.
Astro has already identified Total Video, addressable advertising and outcome-driven solutions as strategic growth areas.
Better measurement could help the company compete for budgets increasingly allocated to digital platforms.
Transformation becomes financially sustainable only when new digital activities are accompanied by structural cost changes.
Astro should continually identify legacy processes, technology and distribution costs that can be simplified as customer behaviour evolves.
Savings should be redirected toward differentiated local content, streaming technology, customer analytics and products with measurable growth potential.
Capital allocation must remain disciplined because adding technology without retiring complexity can increase costs faster than revenue.
Overall, the Astro Business Model Canvas demonstrates how a traditional satellite television company can evolve into a diversified entertainment ecosystem.
The central mechanism remains straightforward. Astro creates and acquires content, aggregates entertainment, distributes it across multiple platforms, attracts audiences and monetises those relationships through subscriptions, prepaid purchases, advertising, connectivity and enterprise services.
What has changed is the architecture surrounding that mechanism.
Satellite television no longer needs to define Astro. Sooka provides a streaming-native proposition, Astro GO extends existing relationships, NJOI provides affordability, Astro Fibre combines connectivity with entertainment, and Astro X3 removes hardware and contractual barriers for another customer segment.
Local content remains especially important because distribution technology can increasingly be replicated. Distinctive Malaysian intellectual property, trusted news, vernacular programming, live sports and established audience relationships are harder for competitors to reproduce.
Astro nevertheless faces significant execution pressure. FY26 reflected a demanding environment characterised by fragmented audiences, piracy, global streaming competition and cost-conscious consumers.
The next stage of transformation should therefore focus less on defending conventional television and more on making Astro indispensable as an entertainment gateway.
If the company can combine local relevance, premium content, streaming flexibility, aggregation, broadband and advertising into a simpler customer proposition, its established reach can remain strategically valuable even as the technology used to consume entertainment continues to change.
This article is provided solely for educational, informational and business-analysis purposes.
The content is based on publicly available information, company disclosures, websites, industry observations and independent strategic interpretation available at the time of writing.
Nothing contained in this article constitutes investment, financial, legal, commercial, technology or other professional advice. Readers should conduct their own research and seek appropriate professional advice before making investment, business or strategic decisions.
This article is not official information from Astro Malaysia Holdings Berhad, Netflix, Telekom Malaysia, Unifi TV, CelcomDigi or any other company mentioned. It should not be interpreted as an official statement, representation, endorsement or communication from those organisations.
Company information, financial performance, products, pricing, technologies, partnerships and market conditions may change over time.
All trademarks, logos, copyrights, company names, product names and other intellectual-property rights belong to their respective owners. Any reference to such names or marks in this article is used solely for identification, educational and analytical purposes.
Explore the Astro Business Model Canvas, including all nine BMC blocks, Value Proposition Canvas, Netflix and Unifi TV comparison, competitive advantages, risks and strategic recommendations updated for 2026.
Discover the Ramly Mokni success story and how he transformed a small halal burger business… Read More
Explore the Rembayung Business Model Canvas, covering all nine BMC blocks, Value Proposition Canvas, De.Wan… Read More
Explore the Kinokuniya Business Model Canvas, covering all nine BMC blocks, Value Proposition Canvas, Barnes… Read More
Explore the Agoda Business Model Canvas, covering all nine BMC blocks, Value Proposition Canvas, Booking.com… Read More
Explore the FedEx Business Model Canvas, nine BMC blocks, Value Proposition Canvas, UPS and DHL… Read More
Explore the Quipper Business Model Canvas, nine BMC blocks, Value Proposition Canvas, Ruangguru and Pahamify… Read More